Buildings with more moving parts
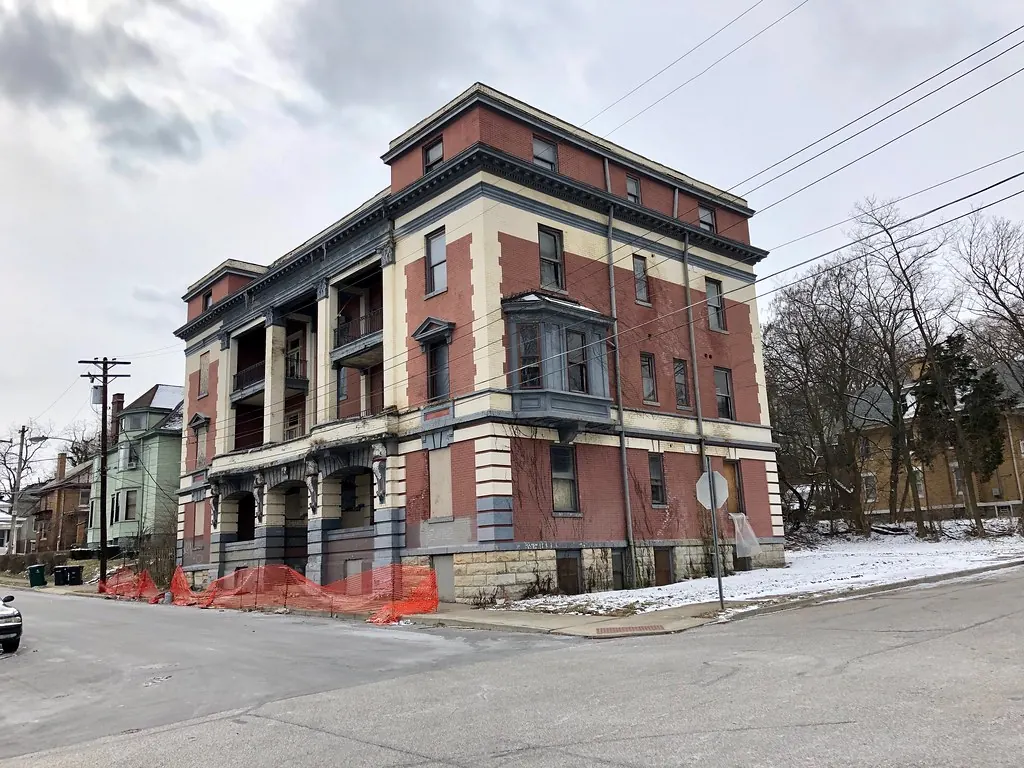
Commercial losses in West Virginia rarely look like the textbook. Downtown blocks in Wheeling, Clarksburg, Fairmont and Bluefield are lined with brick storefronts from the early 1900s, many with apartments upstairs and flat or low-slope roofs hidden behind parapets. Churches across the state carry steep slate or metal roofs and tall stained-glass openings. Newer townhome communities in the Eastern Panhandle and around Morgantown are governed by associations that share responsibility with unit owners. Light industrial and warehouse buildings line the I-79 and I-64 corridors.
Each of those structures can generate an estimate with hundreds of line items, multiple trades and specialty systems, which is exactly where carrier and owner figures drift apart.
Commercial and HOA claim appraisal in WV: our role
When appraisal has been invoked, we can serve as the appraiser for the business or association. We review the commercial property form, any business income coverage, the association’s master policy and governing documents where relevant, and the full claim file. We then build our own scope and price it for the local market.
Where commercial estimates usually split
- Low-slope roofing. Whether a membrane or built-up roof is repairable, and how much tapered insulation and flashing work is needed at parapets and penetrations.
- Rooftop equipment. HVAC units, curbs and electrical disconnects damaged by wind or hail.
- Specialty finishes. Tin ceilings, storefront glazing, millwork and historic masonry.
- General contractor overhead and profit. Often disputed even when the job plainly needs coordination of several trades.
- Code-driven work. Fire separation, egress and accessibility items triggered by the repair, where ordinance or law coverage applies.
- Business income figures. Restoration periods that ignore real lead times for materials and crews in rural counties.
Weather that hits commercial roofs
The June 2012 derecho stripped membranes and toppled rooftop units over a wide part of the state. Heavy wet snow from Superstorm Sandy that October overloaded flat roofs in the central mountains. Ice storms, such as the February 2021 event around Huntington, bring down limbs and power lines onto low buildings. Hail is less frequent than in the plains, but it does reach the Ohio Valley and the Eastern Panhandle. For roof-specific issues, see our roof and hail claim page.
Working with boards and owners
We know association boards often have to explain decisions to members, and business owners need to plan around downtime. We provide written summaries of the disputed items, explain the reasoning in plain terms and keep the board or owner informed at each stage. We do not give legal advice, and we do not negotiate coverage. Our job is a defensible number.
Getting started
- Collect the full policy, including all endorsements and the schedule of locations.
- Pull maintenance and roof records; they help answer wear-and-tear arguments.
- Gather invoices for emergency services such as tarping, board-up and water extraction.
- Assemble financial records if business income is part of the claim.
Once we have the file, we usually identify the largest disputed categories first, since a handful of items such as roofing, rooftop equipment and contractor overhead tend to drive most of the gap on a commercial or association claim. That early read helps an owner or board decide whether appraisal is worth the time and shared cost, or whether a documented supplement request may be enough.
Questions about this service
Can an HOA board hire its own appraiser for a master policy claim?
Generally the named insured under the master policy chooses its appraiser when appraisal is invoked. Boards should confirm their authority under the governing documents before acting.
Do you handle business income disputes in appraisal?
Some policies allow appraisal of business income amounts and some do not. We can review the wording and help document the restoration period if it is within scope.
Is appraisal useful for a church with a slate roof?
It can be, especially when the dispute is about repair versus replacement or matching historic slate. Coverage questions, such as age or wear exclusions, are a separate matter.