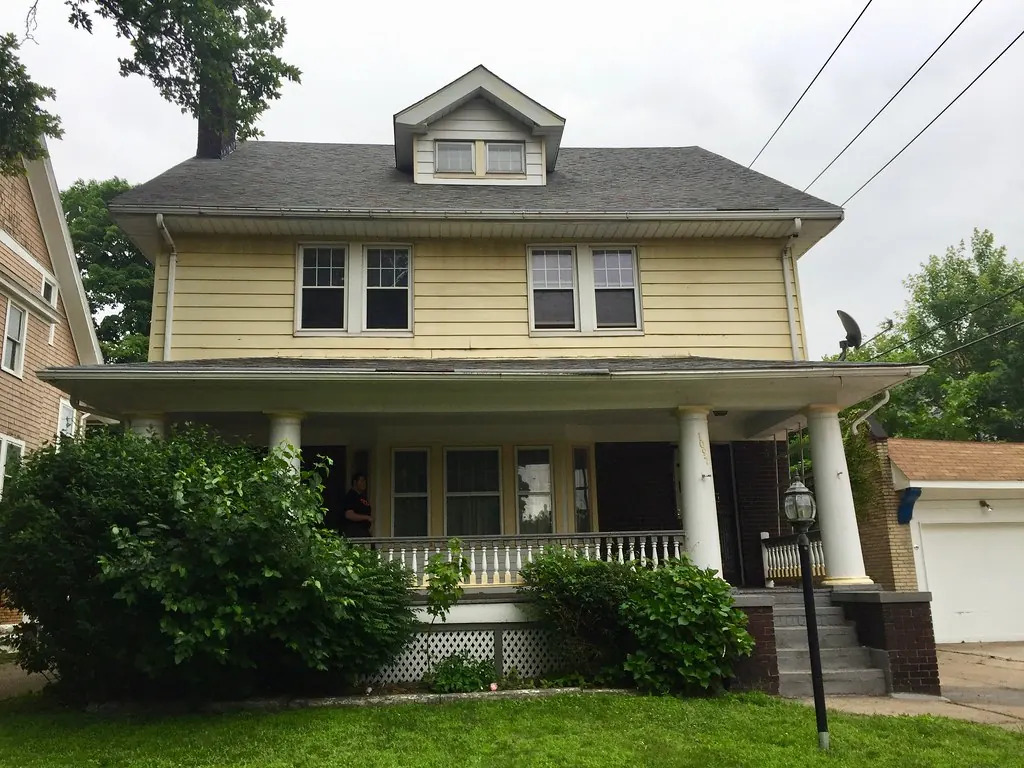
The houses we see most often
West Virginia’s housing stock is old and varied, and that shapes almost every claim. River towns along the Kanawha, Ohio and Monongahela are full of wood-frame homes built between 1900 and the 1950s, often with plaster walls, balloon framing and several generations of additions. Coal-camp houses in the Southern Coalfields share walls, rooflines and quirks with their neighbors. Manufactured homes are common in every region. Newer vinyl-sided subdivisions are spreading in Berkeley and Jefferson counties and around Morgantown, while cabins and second homes cluster near Snowshoe, Canaan Valley, Davis and the New River Gorge.
A carrier’s estimating software tends to assume a generic house. When the real home has plaster over lath, a slate porch roof or a crawlspace reached through a two-foot hatch, the line items often need to change.
How a homeowners insurance appraiser in WV approaches the file
We start with your policy’s declarations and loss settlement terms, then compare every estimate already in the file. Next we inspect and document the home ourselves. If appraisal has been or will be invoked, we serve as your appraiser; if not, we can prepare a detailed estimate review you can use in your own negotiation.
Common gaps in residential estimates
- Plaster and lath priced as drywall. Repairing or matching plaster takes different labor and materials.
- Partial painting. Painting one wall of a room when the finish cannot be blended.
- Flooring continuity. Replacing only the damaged boards of an older hardwood floor that runs through several rooms.
- Manufactured home specifics. Skirting, belly wrap, tie-downs and specialty components priced as if the unit were site-built.
- Access and hauling. Steep driveways, narrow hollow roads and long distances to a landfill that add labor and disposal cost.
- Contents. Depreciation applied too aggressively or items left off the inventory entirely.
Perils that drive home claims here
Falling trees are a leading cause of dwelling damage in a state that is roughly three-quarters forest. Add severe thunderstorms and derechos, wet snow loads, ice storms, frozen pipes, kitchen and chimney fires, and the occasional hail swath in the Ohio Valley or Eastern Panhandle. Each brings its own estimating arguments, and several have their own pages on this site.
Two common West Virginia problems usually sit outside a standard homeowners form: flood and landslide. Mine subsidence is typically handled through a separate endorsement. If your claim touches any of these, expect a coverage discussion before any appraisal discussion.
What you can do this week
- Photograph every room, including ceilings, attic and crawlspace, before temporary repairs.
- Keep damaged materials or samples until the carrier has had a chance to see them.
- Get the carrier’s estimate in its full line-item form, not just a summary letter.
- Write down every conversation with the adjuster, with dates.
- Send us the file so we can tell you whether the gap justifies appraisal.
If you live in one of the larger metros, our local pages for Charleston and Morgantown describe the housing and storm patterns we see there. Wherever the home sits, the goal is the same: an estimate that reflects the house you actually own, priced for the place where it will be repaired, so the conversation with your carrier is about real numbers rather than assumptions.
Questions about this service
Can I use appraisal for a manufactured home claim in West Virginia?
Often, yes, if the policy covering the home includes an appraisal clause. Manufactured home forms differ from standard homeowners forms, so confirm the clause is there and read how it works.
My adjuster priced plaster walls as drywall. Is that an appraisal issue?
It can be. Disagreements over the method and cost of repair are generally about the amount of loss, which is what appraisal is meant to resolve.
Will you look at a contents claim as well as the house?
Yes. We review contents inventories, pricing and depreciation along with dwelling items, since both often sit in the same disputed estimate.