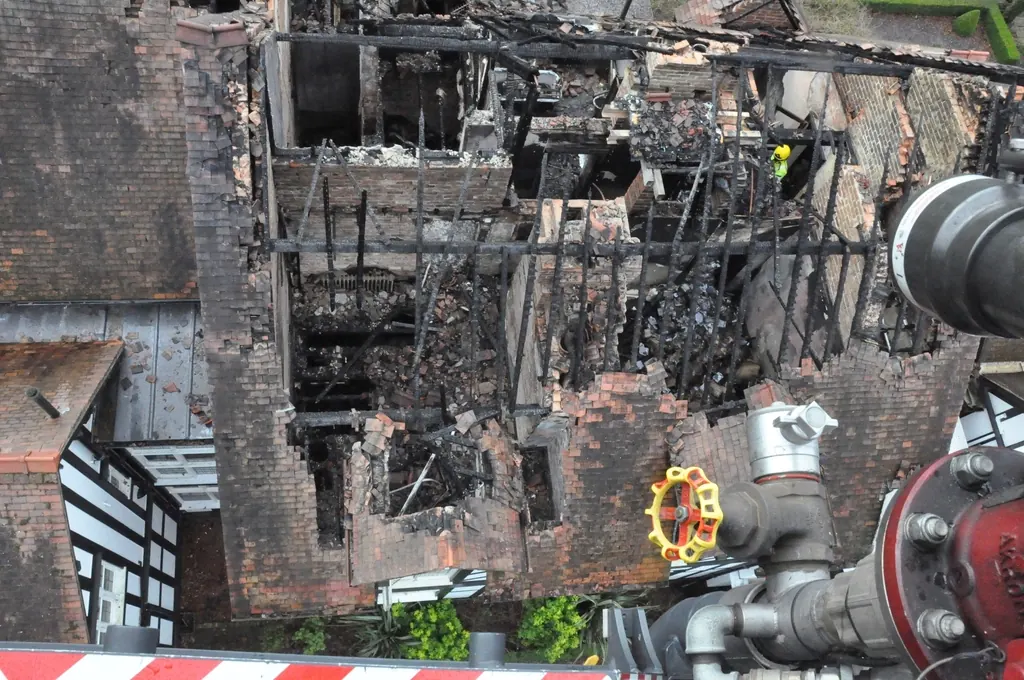
How fires start in Mountain State homes
Wood stoves and coal stoves still heat many homes in West Virginia, especially in rural counties and the Southern Coalfields. Chimneys that serve them need regular cleaning, and creosote buildup or a cracked flue liner can start a fire inside the walls. Older wood-frame houses from the early twentieth century may have outdated wiring, knob-and-tube circuits, or overloaded panels. Kitchen fires happen everywhere. In dry autumns and springs, wildfires burn through forested hillsides in the southern counties and send smoke into nearby homes.
Where fire and smoke estimates diverge
Fire and smoke claim appraisal in WV usually centers on how far damage spread, which materials can be cleaned instead of replaced, and how contents were valued. A fire confined to one room can still push smoke and soot through ductwork, attic spaces and wall cavities.
Typical disputes
- Clean versus replace. Whether smoke-stained drywall, trim, cabinets or flooring can be cleaned and sealed, or must be replaced.
- HVAC and ductwork. Duct cleaning priced when soot has made replacement more realistic.
- Odor control. Sealing, deodorizing and repeated treatments left out of the scope.
- Structural framing. Charred joists or rafters that were sistered in the estimate rather than replaced.
- Code upgrades. Electrical and smoke detector work required when walls are opened, where ordinance or law coverage applies.
- Contents. Inventory gaps, cleaning versus replacement decisions and depreciation rates.
- Additional living expense. How long the family realistically needs to be out of the home, given contractor availability in rural areas.
Older houses, special problems
A fire in a brick Victorian in Wheeling or Parkersburg can damage plaster ceilings, ornate trim and hardwood floors that are hard to reproduce. Coal-camp houses in McDowell or Mingo counties may share walls or rooflines with a neighbor, complicating the scope. Manufactured homes often lose so much to heat and smoke that a total loss is the realistic answer, and the dispute shifts to the home’s value. Cabins near the New River Gorge or in the Greenbrier Valley may sit far from the nearest restoration contractor, adding travel and mobilization costs.
Wildfire smoke in the south
When wildfires burn in Mingo, Logan, Wyoming, McDowell or nearby counties, nearby homes may take on smoke odor and fine ash without any flame contact. Some policies cover smoke damage from a nearby fire; the scope may include cleaning surfaces, replacing HVAC filters, cleaning ducts and treating soft goods. Coverage depends on the policy wording, so check your form before assuming either way.
Building a fire claim file
- Get the fire department report number and any investigator’s contact.
- Photograph every room, including those that look undamaged, since smoke spreads.
- Start a contents inventory with descriptions, ages and approximate prices.
- Keep receipts for hotel stays, meals and other added living expenses.
- Ask for the carrier’s structure and contents estimates separately.
For questions on depreciation and holdback, see our guide on depreciation and holdback, and for line-by-line estimate checks, our estimate review service.
A note on timing
Fire claims rarely move quickly, and rushing can leave items out. It is often wiser to let the full extent of smoke and soot damage become clear, and to complete the contents inventory carefully, before agreeing to a final number. Many policies set time limits for certain steps, so check your form and keep the carrier informed in writing as you go.
Questions about this service
Is smoke damage from a neighbor’s fire covered?
Many homeowners policies cover smoke damage even if the fire was not on your property. Coverage depends on the policy wording, so check the perils section of your form.
Can appraisal decide whether my house is a total loss?
Whether repair costs exceed value is often part of the amount of loss, so it may be decided in appraisal. Policy limits and coverage questions remain separate.
Does appraisal cover my contents inventory?
If the dispute is about the value of contents and the policy’s appraisal clause applies, contents can generally be included alongside the structure.