A coverage built for coal country
West Virginia has a mine subsidence insurance program operated with the state Board of Risk and Insurance Management (BRIM). Insurers that write dwelling coverage in the state are generally required to offer mine subsidence coverage as an endorsement. The coverage limit is capped, commonly described as up to $75,000 for a dwelling, and it carries its own deductible. Details change from time to time, so check your endorsement and declarations for the limit, deductible and conditions that apply to you.
Because the limit is capped, the dispute on a subsidence claim is often less about the total value of the house and more about whether the damage is subsidence at all, and how much of the capped amount the repairs justify.
What a mine subsidence claim appraiser looks at
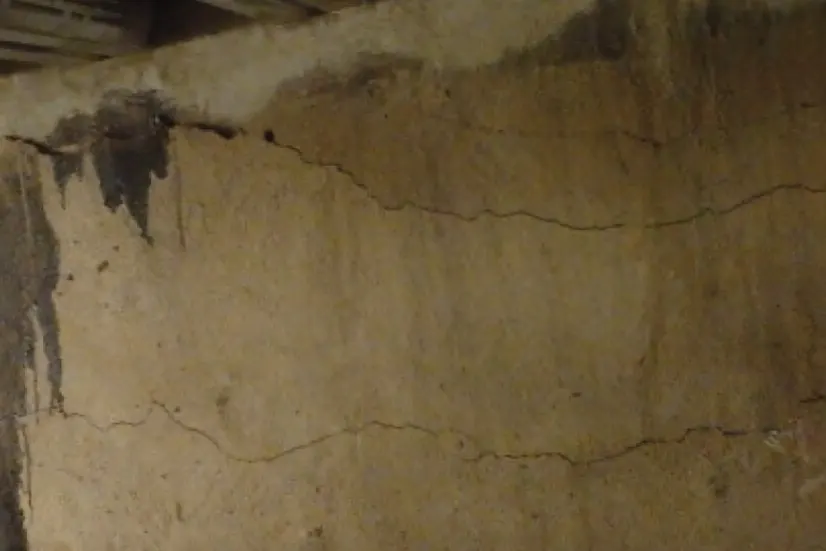
Subsidence damage tends to develop over time. Cracks in foundation walls and slabs, doors and windows that stick, separated chimneys, sloping floors and broken utility lines are common signs. We document each one with photos, measurements and notes on progression, then build a repair estimate that reflects what stabilizing and restoring the structure realistically takes.
Points that are commonly disputed
- Cause. Whether cracking reflects subsidence from mine voids, ordinary settlement, poor original construction, expansive soils or a slide.
- Foundation scope. Underpinning, piering or wall replacement versus patching cracks.
- Related damage. Interior drywall and plaster cracking, door and window adjustments, and plumbing repairs tied to the movement.
- Deductible and limit math. How the endorsement’s deductible and cap interact with the repair estimate. Our mine subsidence limit calculator can help.
- Prior repairs. Earlier patchwork that complicates the timeline.
Subsidence is not landslide
This distinction matters more in West Virginia than almost anywhere. Steep slopes, heavy rain and road cuts make landslides a frequent problem, and standard homeowners policies typically exclude earth movement, including landslides, mudflow and sinking. The mine subsidence endorsement usually covers collapse of underground mine workings, not soil sliding downhill. A house can crack for either reason, and sometimes both. Our guide to landslide versus mine subsidence claims explains the differences in more depth.
Appraisal cannot create coverage. If the damage is ruled a landslide and the policy excludes earth movement, an appraisal panel will not change that outcome.
Where subsidence claims come from
Underground mining has been widespread across the Northern Panhandle, the North-Central counties along I-79 around Fairmont, Clarksburg and Morgantown, and throughout the Southern Coalfields in Logan, Mingo, McDowell, Raleigh, Boone and Wyoming counties. Many homes in these areas were built on top of or near old workings, some long before modern mapping. Coal-camp houses and older frame homes on block foundations show subsidence damage differently than newer homes on poured walls.
Steps if you suspect subsidence
- Confirm the mine subsidence endorsement is on your declarations page.
- Photograph and date every crack, and mark the ends with pencil to track growth.
- Report the claim promptly to your insurer and keep a copy of the notice.
- Ask what engineering inspection will be done and request a copy of the report.
- Get an independent repair estimate if the carrier’s figure seems low.
Questions about this service
Is mine subsidence coverage automatic on my West Virginia homeowners policy?
Not always. Insurers generally must offer it, but you may need to accept or keep the endorsement. Check your declarations page to see if it is listed.
What is the most the mine subsidence endorsement will pay?
The limit is capped and commonly described as up to $75,000 for a dwelling, with its own deductible. Read your endorsement for the exact figures that apply to your policy.
My insurer says my cracks are from a landslide. What can I do?
That is a cause and coverage question, which appraisal usually does not decide. An independent engineer and a West Virginia attorney may help you evaluate the denial.