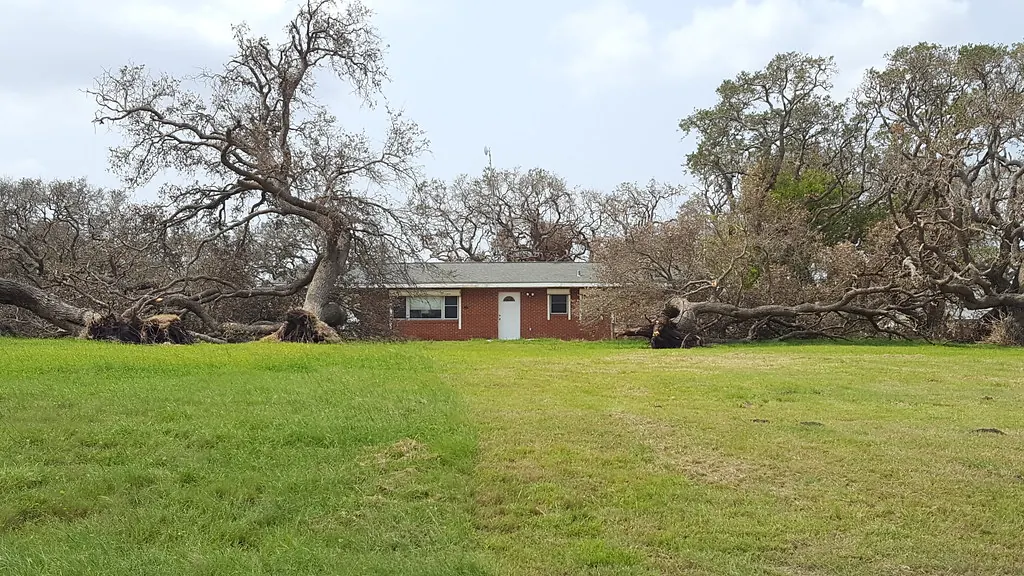
A history written in fallen timber
On June 29, 2012, a derecho raced across the state on a hot summer evening. It knocked out power to a large share of West Virginians for days, and in many hollows the outage lasted longer because crews first had to cut through downed trees. That storm remains the reference point for straight-line wind here. Decades earlier, on June 23, 1944, the Shinnston tornado tore through Harrison County and became the deadliest tornado in the state’s history. Tornadoes are less common in the mountains than in flatter states, but they do happen, and severe thunderstorms with damaging gusts arrive every warm season.
Wind, derecho and tornado claim appraisal: what changes on a wind file
Wind claims are rarely just about shingles. Trees dominate. With roughly three-quarters of the state in forest, a wind event usually means limbs and trunks on roofs, porches, vehicles, fences and outbuildings. The arguments then move to tree removal limits, debris hauling, framing repairs and what happens to the trees that fell but hit nothing.
Line items that are frequently disputed
- Tree removal and debris limits. Many policies cap tree removal, and the cap may apply differently when a tree strikes a covered structure. Check your form.
- Structural framing. Rafters, ridge boards and wall studs cracked by a falling trunk, sometimes hidden behind finished ceilings.
- Siding and matching. Older vinyl or aluminum siding where replacement pieces don’t match the faded original.
- Outbuildings. Barns, pole buildings and detached garages, often with metal roofs, that fall under other structures coverage.
- Crane and equipment charges. Removing a large oak from a house on a steep lot may need equipment the estimate ignores.
- Mitigation. Tarping, board-up and water extraction costs incurred in the first days after the storm.
Regions and building types we see after wind events
Ridge-top homes in the Potomac Highlands and Greenbrier Valley take direct gusts. In the North-Central counties along I-79 and in the Mid-Ohio Valley, mature hardwoods line older neighborhoods, so a single storm can drop dozens of trees onto houses in Clarksburg, Fairmont or Parkersburg. Manufactured homes in the Southern Coalfields and Metro Valley are especially vulnerable to uplift and need careful attention to tie-downs, skirting and underbelly damage. Newer homes in the Eastern Panhandle tend to see siding, soffit and roof covering losses.
Building the estimate after a tree strike
- Document the tree in place before removal, from several angles, if it is safe.
- Photograph the attic and interior ceilings where the trunk landed.
- Keep invoices from the tree service, broken out between emergency removal and later cleanup.
- Ask the carrier how it applied any tree or debris limit, in writing.
For roofing details, see our roof and hail claim page, and for photo tips, our guide to documenting storm damage in West Virginia.
When appraisal helps and when it doesn’t
If the carrier accepts that wind caused the damage but disagrees about how much framing, roofing or siding needs replacing, appraisal can be a practical tool. If the carrier says the tree was dead or diseased and denies the claim on that basis, the dispute may be about coverage. In that situation, talk to a West Virginia attorney about your options before relying on appraisal alone.
Questions about this service
Does my policy pay to remove a tree that fell in my yard but hit nothing?
Often only in limited situations, such as when the tree blocks a driveway or ramp, and usually subject to a small limit. Read the debris removal and trees sections of your policy.
Was the 2012 derecho a tornado?
No. A derecho is a long-lived line of straight-line wind damage from a cluster of thunderstorms. Claims are usually handled as windstorm losses rather than tornado losses.
Can appraisal cover damage to my barn or pole building?
If the outbuilding is covered, typically under other structures or a farm form, and the dispute is about the amount of loss, it can generally be included in appraisal.